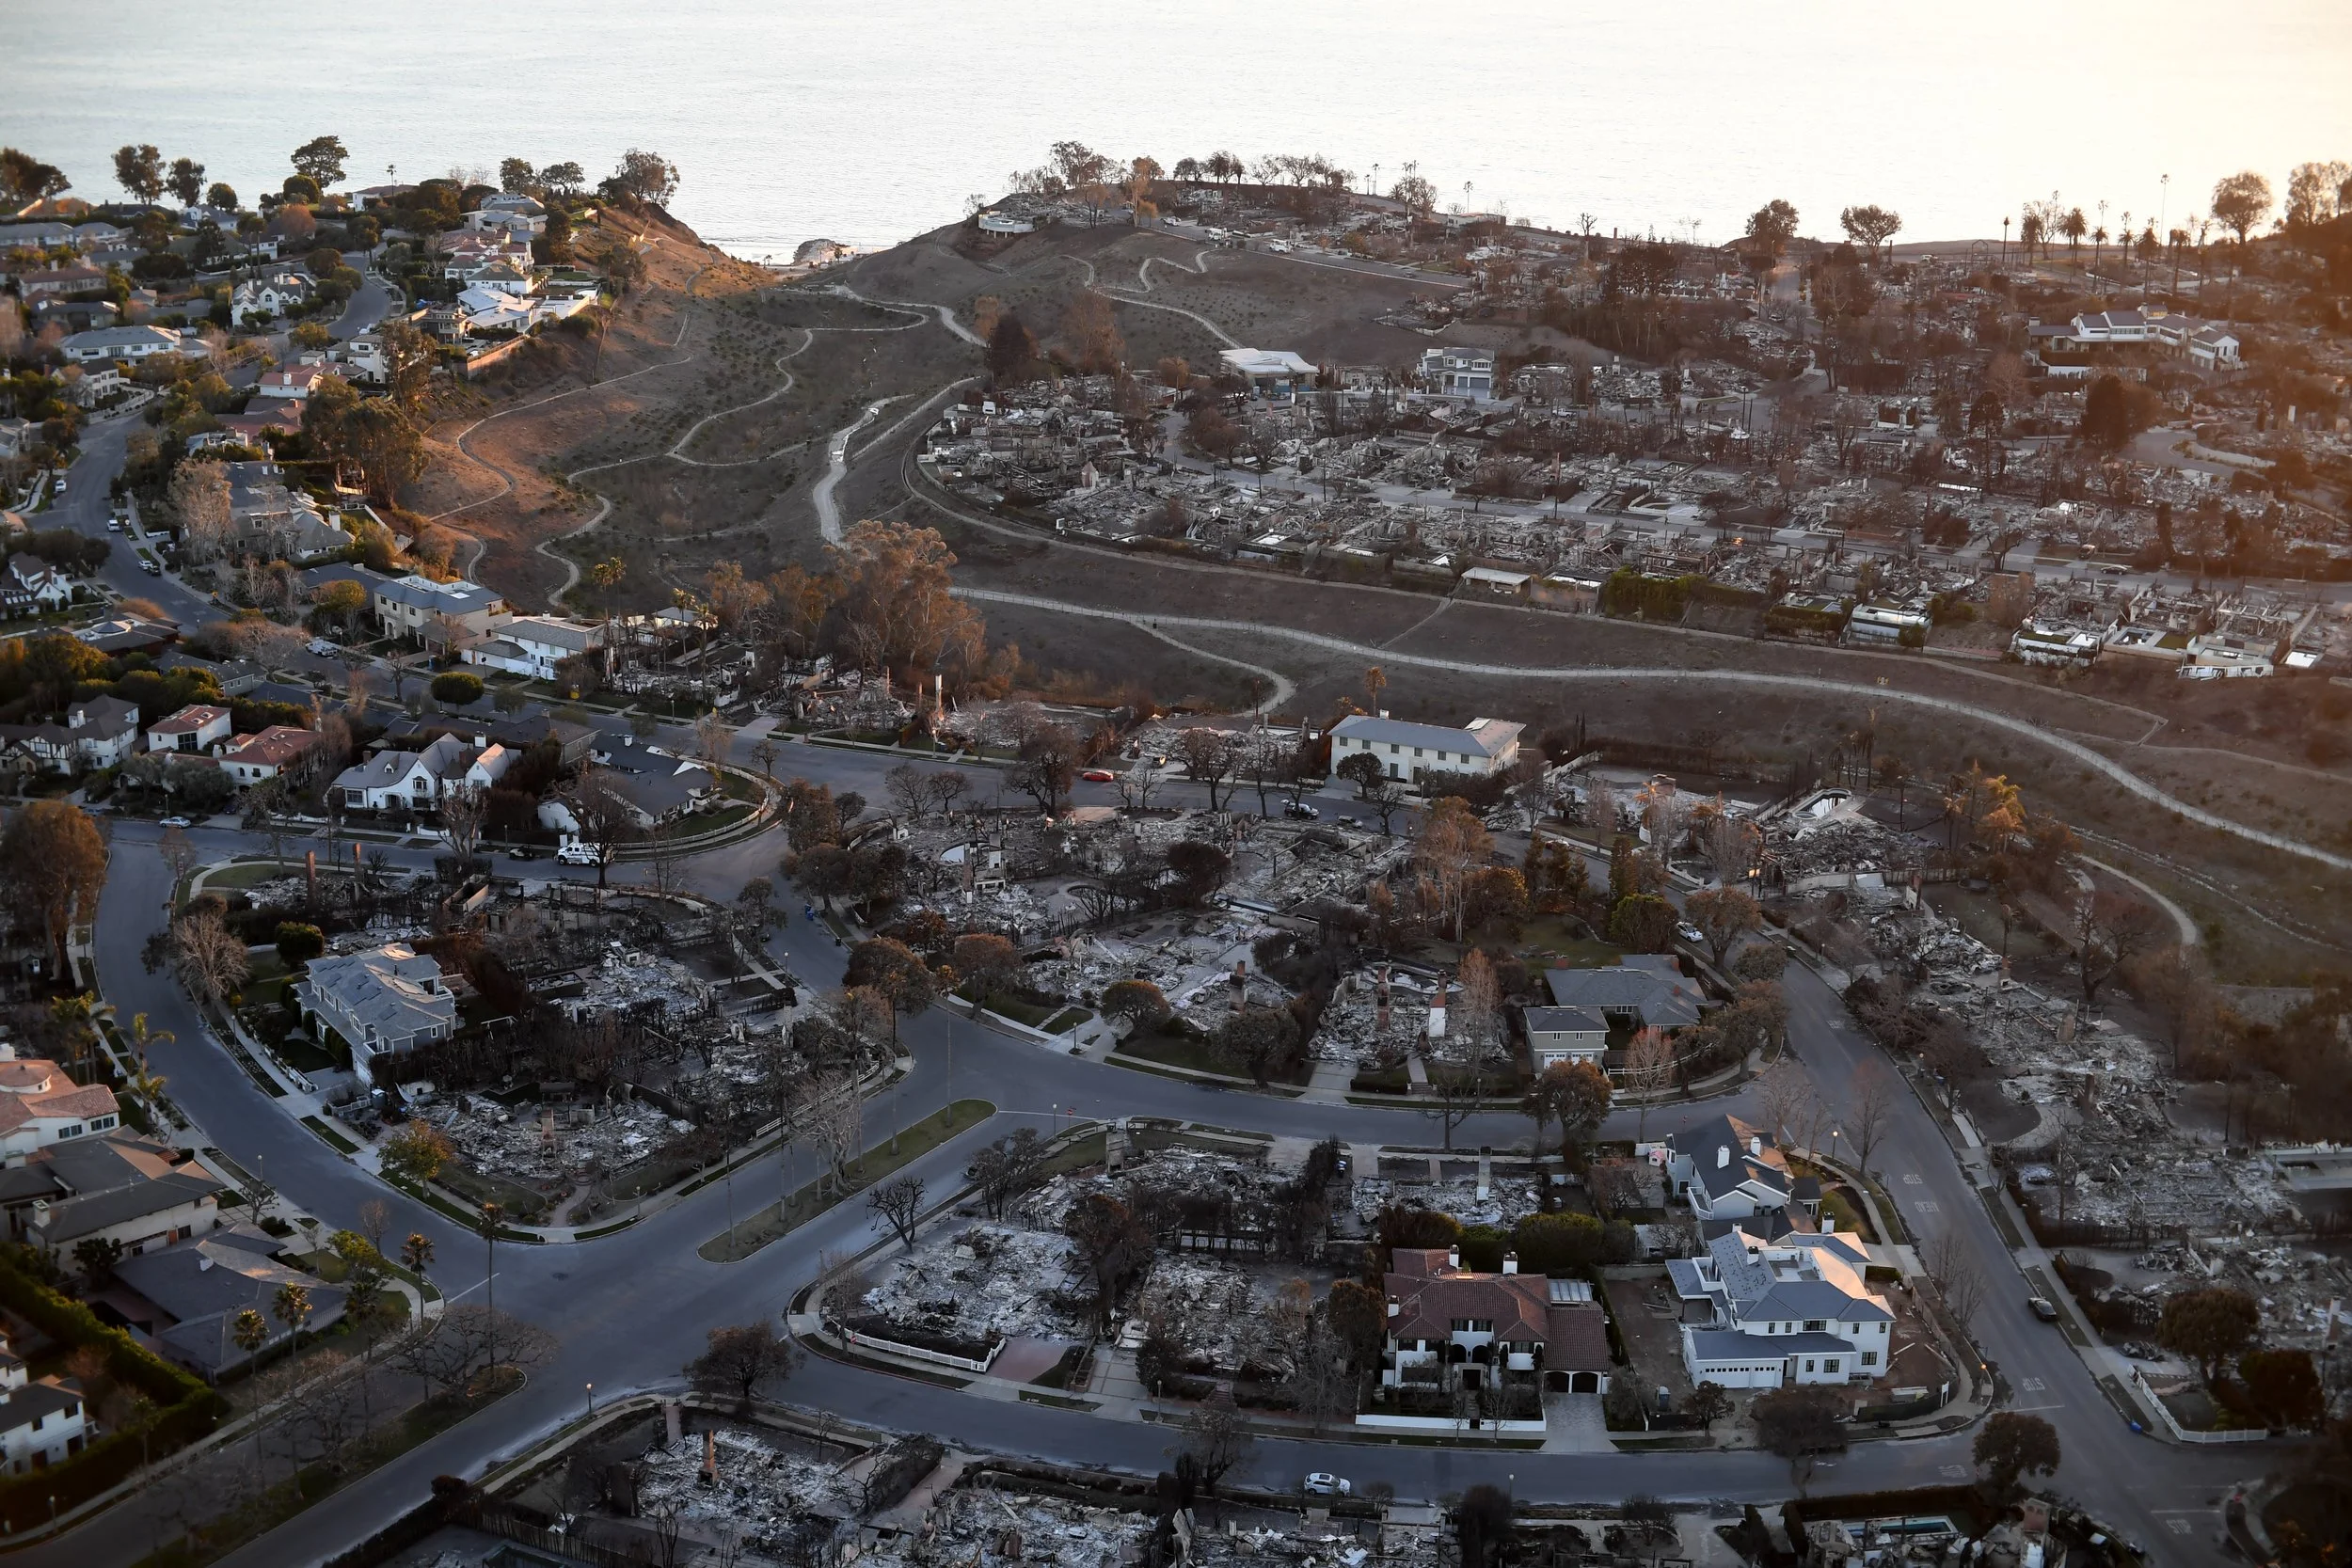
PACIFIC PALISADES RENTAL HOUSE
Pacific Palisades Fire Claim: MLA’s ruthless advocacy pushed back against significant delays by the carrier and lifted a $744,174.99 offer to $1,673,650.48, an approximately 125% increase.
Rental House - Pacific palisades, california
Initial Offer: $744,174.99
Settlement: $1,673,650.48
Like many of the structures affected by this devasting wildfire that occurred in early January of 2025, the owners’ property completely burned down. The policyholders, a retired couple, figured the insurance claim should be easy, “We assumed that they would write us a check for the policy limits”. Unfortunately, this did not happen. By the end of March 2025, MLA was contacted by the owners and commenced with handling the claim.
Through online technology, interviews with the policyholders, old videos and pictures taken in the home, and a handwritten sketch – MLA forensically created a detailed, room by room replacement estimate of the destroyed home and detached garage. The gross damage (before applicable sub-limits) was estimated by MLA at $1,954,898.05 and submitted on April 29, 2025, less than 30 days after MLA’s engagement. It wasn’t until May 19, 2025, over 4.5 months after the wildfire, that the insurer provided its initial estimate of $744,174.99.
On June 4, 2025, MLA submitted a detailed delta report that specifically addressed the deficiencies in the carrier’s offer including old photos that illustrated omissions of items in the home that were not in the insurer’s estimate.
Unfortunately, one of the realities after a widespread disaster is simply not getting the proper attention to your insurance claim. It is our opinion that there are too many adjusters and/or estimators communicating and compiling estimates on insurers’ behalf without the proper experience after a disaster. This claim was also transferred to a different carrier adjuster no less than six (6) times.
On December 4, 2025, MLA wrote, “It has been SIX (6) MONTHS or one half of one year since we sent REDACTED the partial photo report illustrating deficiencies in its dwelling estimate. Despite indisputable mistakes in the REDACTED dwelling estimate and several promises to address it including your most recent one on 10/1/25, there has been no material response and/or revisions to REDACTED dwelling estimate yet. This is an outrageous amount of time to delay the adjustment process.”
Through our observations, the claim was reassigned four (4) times in the eight (8) months following the 6/4/25 submission. MLA followed up regularly, filed two complaints with the Commission of Insurance, and contacted and talked to numerous supervisors at the carrier before it materially commenced revising its estimate.
On February 7, 2026, over eight (8) months after MLA detailed the deficiencies in their initial estimate, the insurer revised its net offer, after applicable sublimit(s), to $1,638,818.99. On September 29, 2026, the dwelling and garage settled for an equitable net amount of $1,673,650.48, which is approximately 125% more than the insurer’s initial offer.